

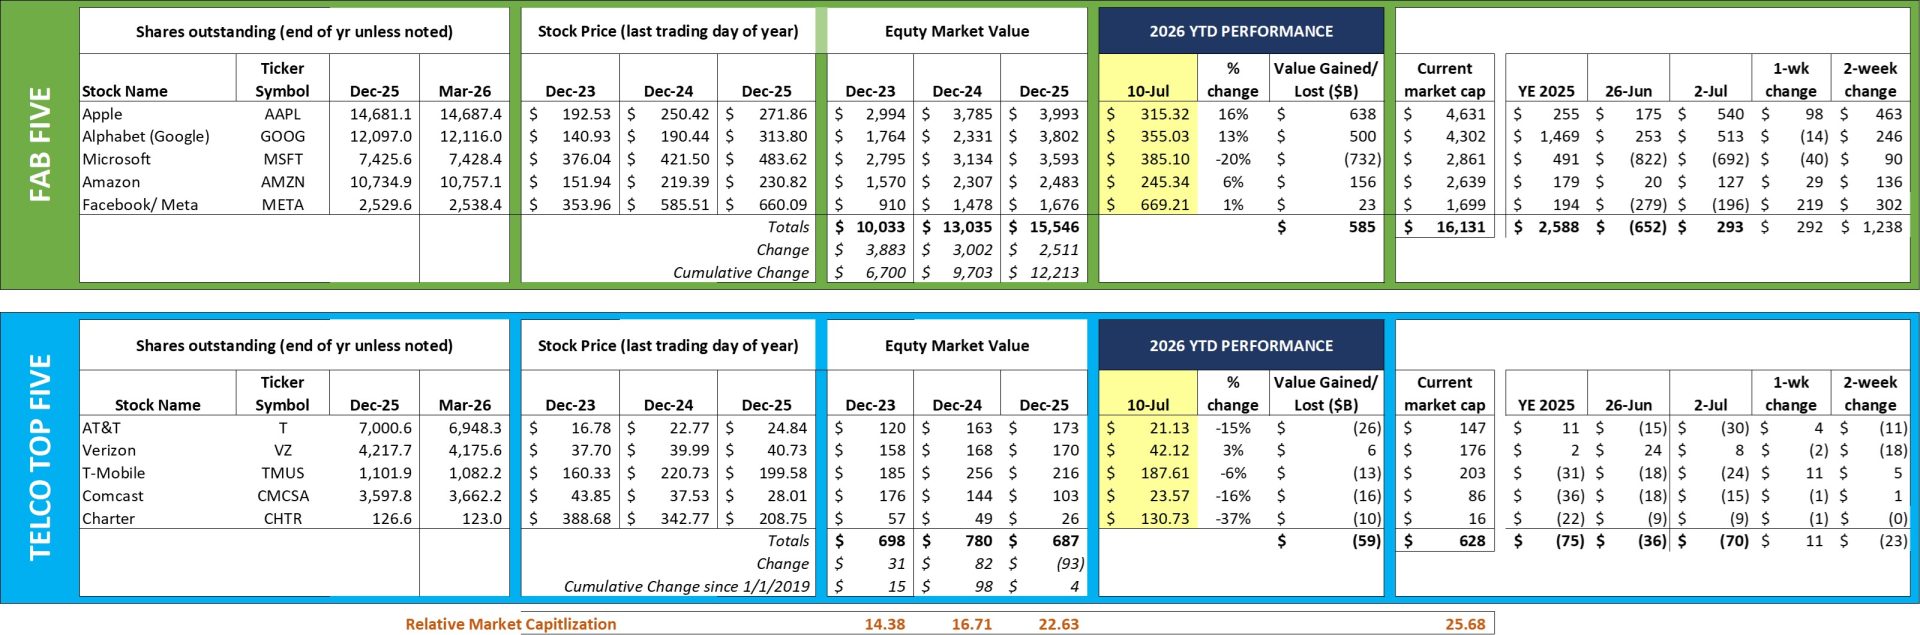
As predicted, investors returned after the Fouth of July holiday and were in a buying mood. The Fab Five added to the Holiday week gains with an additional $292 billion in market capitalization. Meta led the parade, with over $300 billion in value growth in the last two weeks.
Driving Meta’s gain this week was their announcement that they were going to produce their own AI chip (CNBC story on this and their cloud announcement here). We think that Meta will build incremental value blocks that will enable their internal (core) network to expand rapidly. Unlike their other Fab Five colleagues, Meta has to enable AI across each of their social media platforms to remain relevant (and they have the ghost of AOL to remind them of the consequences of inaction). This is an important distinction that is often overlooked by the analyst community.
We promised to dive into the macroeconomic picture in this Interim Brief. Here are the headlines:
- Headline disinflation (month-over-month only) will be driven by lower energy prices
- Real wage growth will resume (wages will grow faster than headline inflation) throughout the summer
- 2Q corprate profits will continue to show broad double-digit growth
- Retirements are rising again, not falling, but post-retirement reentry into the workforce is also growing
- Capital investments beyond AI will show surprsing growth thanks to tax code changes
- States that have (or have the capacity to) embraced the manufacturing boom are going to disproportionately win
That is a lot to digest, and there are many variables. Here are a few supporting statistics:
- Truflation data (we use this as a proxy for direction but not necessarily level). X posts here. Using a 20% drop from peak, this would imply a headline rate around 3.2-3.3% and an ex-food and energy rate of 2.5-2.6%. Per AAA, gas prices are likely down 11-15% in the next report which will present a very strange data pair – low monthly inflation but continued higher than expected year-over-year marks.
- TD Ameritrade’s March assessment of capital spending (here) shows a mixed picture. AI spending up (and taking a lot of labor) but so are non-AI construction jobs. Expectations have been lowered for non-AI spending in 2026 and 2027 and they will be reset even with higher than desired interest rates.
- The Bureau of Labor Statistics post on older Americans workforce participation rate (here). The chart in the link says it all – more people are working after the traditional retirement age of 65. This can happen for various reasons, but older America is actually keeping the labor participation rate from falling faster.
- Census Bureau Household Income growh (here). We cited this in a previous Brief, but the assessment of household income growth favoring blue collar trade jobs (and not white collar) is going to continue through (and past) the AI investment cycle.
When you put this all together, the picture for broadband and wireless providers is bright. Household incomes are rising (and taxes are flat to shrinking in many states), spending is rising (and broadening), and jobs for all ages are available in many areas. Productivity now taks center stage, and AI is the lead actor.
File is below (which has an new 2Q earnings calendar tab). Please direct all comments and questions to sundaybrief@gmail.com.
Important disclosure: The opinions expressed in The Sunday Brief are those of Jim Patterson and Patterson Advisory Group, LLC, and do not reflect those of CellSite Solutions, LLC, or Fort Point Capital.
