

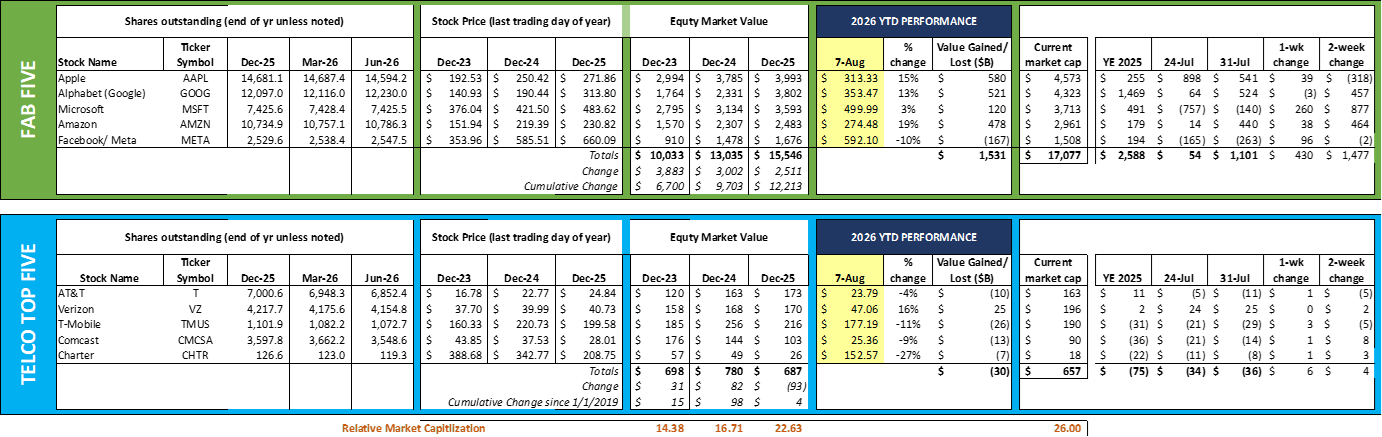
This was another strong week for the Fab Five (+$430 billion one-week, $1.48 trillion two-week gains) with continued strength from Microsoft (+$260 billion, $877 billion) leading the way. Microsoft is now higher for the year for the first time.
To give you an idea of the magnitude of the snapback, the 10-day Meta chart tells the story (courtesy of Yahoo! Finance):
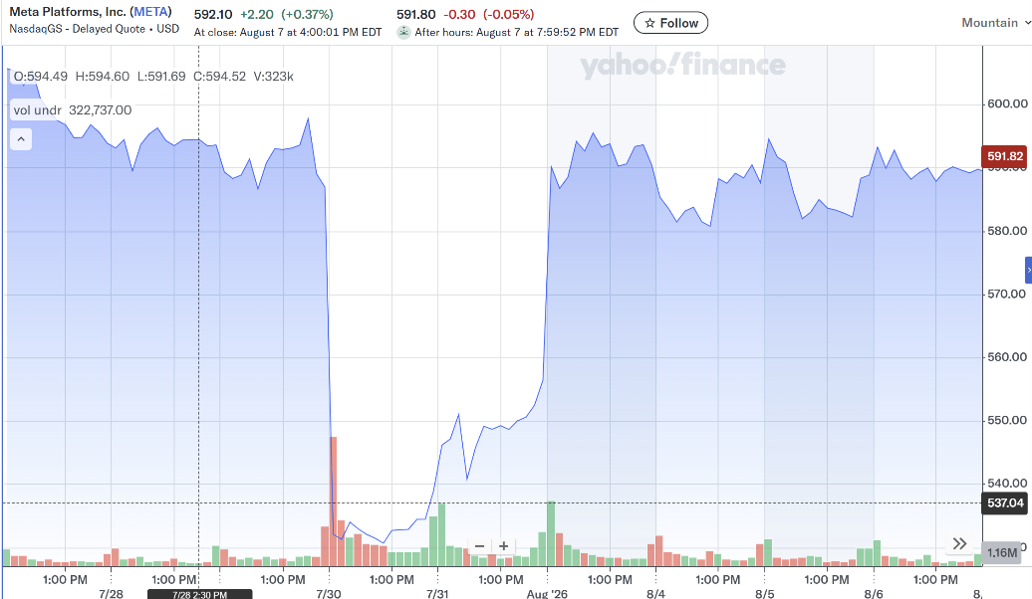
On Tuesday, the Fab Five suddenly came back in favor. It was as if the capital-intensive earnings release (and the corresponding free cash flow concerns) never happened.
The Telco Top Five continue to be out of favor. The winner over the last two weeks has been Comcast (+$8 billion) as the analyst community begins to see the myriad of opportunities that the Philadelphia media conglomerate faces. Universal Studios also is enjoying the success of Christopher Nolan’s The Odyssey which recently surpassed $1.1 trillion globally. Outside of that news, it is hard to get excited about traditional telecom until Thursday’s California PUC meeting, where the Charter acquisition of Cox is expected to receive their last state approval. We anticipate a quick (end of August) close.
On the macro front, the Bureau of Labor Statistics released the latest employment report, and the results were less than expected. May and June were revised downward by 103,000 and July resulted in a net loss of 23,000. Private payrolls were positive, but government (led by local government, likely seasonal teacher layoffs) was negative.
We continue to believe that there is a substantial shortage of selected trade resources, and that many non-AI projects are being delayed simply because of supplies and labor sourcing. As we have reported previously, the impact of Artificial Intelligence is disproportionately impacting the top two quintiles of the workforce (mostly white-collar) and not having a meaningful impact (yet) on the lower three quintiles. Major retailers report earnings the week of August 17 and we will be watching these reports closely to confirm middle-income consumption strength.
Next week, we dive into AT&T and T-Mobile. File is attached. Have a great week!
